RICS Help to Buy valuations
Your equity loan, answered.
The independent RICS valuation your Help to Buy repayment is based on. Compare quotes from Registered Valuers who know the process.
Free for homeowners · No obligation · RICS Registered Valuers only
Checks matched to the service
We verify the business and complete the checks required for that service before a RICS valuer can receive an enquiry.
See what we checkYou control how many contact you
You choose how many matched professionals get in touch - and your details go only to those businesses.
Compare with no obligation
Your matches quote you directly. Compare price, what's included, availability and experience, then decide in your own time.
What is a Help to Buy valuation?
When you repay a Help to Buy equity loan - whether you're selling, remortgaging or settling it early - the amount you repay is a percentage of your home's current market value, not what you originally paid. That value must come from an independent RICS Registered Valuer, in a 'red book' report that meets the loan administrator's rules: physical inspection, comparable evidence, and no connection to you or the sale.
The valuation directly sets the size of your repayment: on a 20 per cent loan, every £10,000 of value moves what you owe by £2,000. An accurate, well-evidenced valuation is worth far more than its fee.
When do you need one?
You'll need a compliant RICS valuation when you're:
- Selling a home bought with a Help to Buy equity loan
- Remortgaging while the loan is outstanding
- Repaying (redeeming) the loan early, in full or in part
- Refreshing an expired valuation - reports are typically valid for 3 months, with extensions possible on an active redemption
What does it cost?
A Help to Buy valuation typically costs £150 to £350, depending on the property's value and region. The report must meet the administrator's specific requirements, so confirm the valuer does Help to Buy work when you compare - every valuer on Homeply quoting for this service does.
Mortgage lender valuations and estate agent appraisals don't count: the administrator only accepts an independent RICS valuation.
Run your own numbers in our survey cost calculator, then compare real quotes against it.
How it works
A simpler way to find the right help.
 1
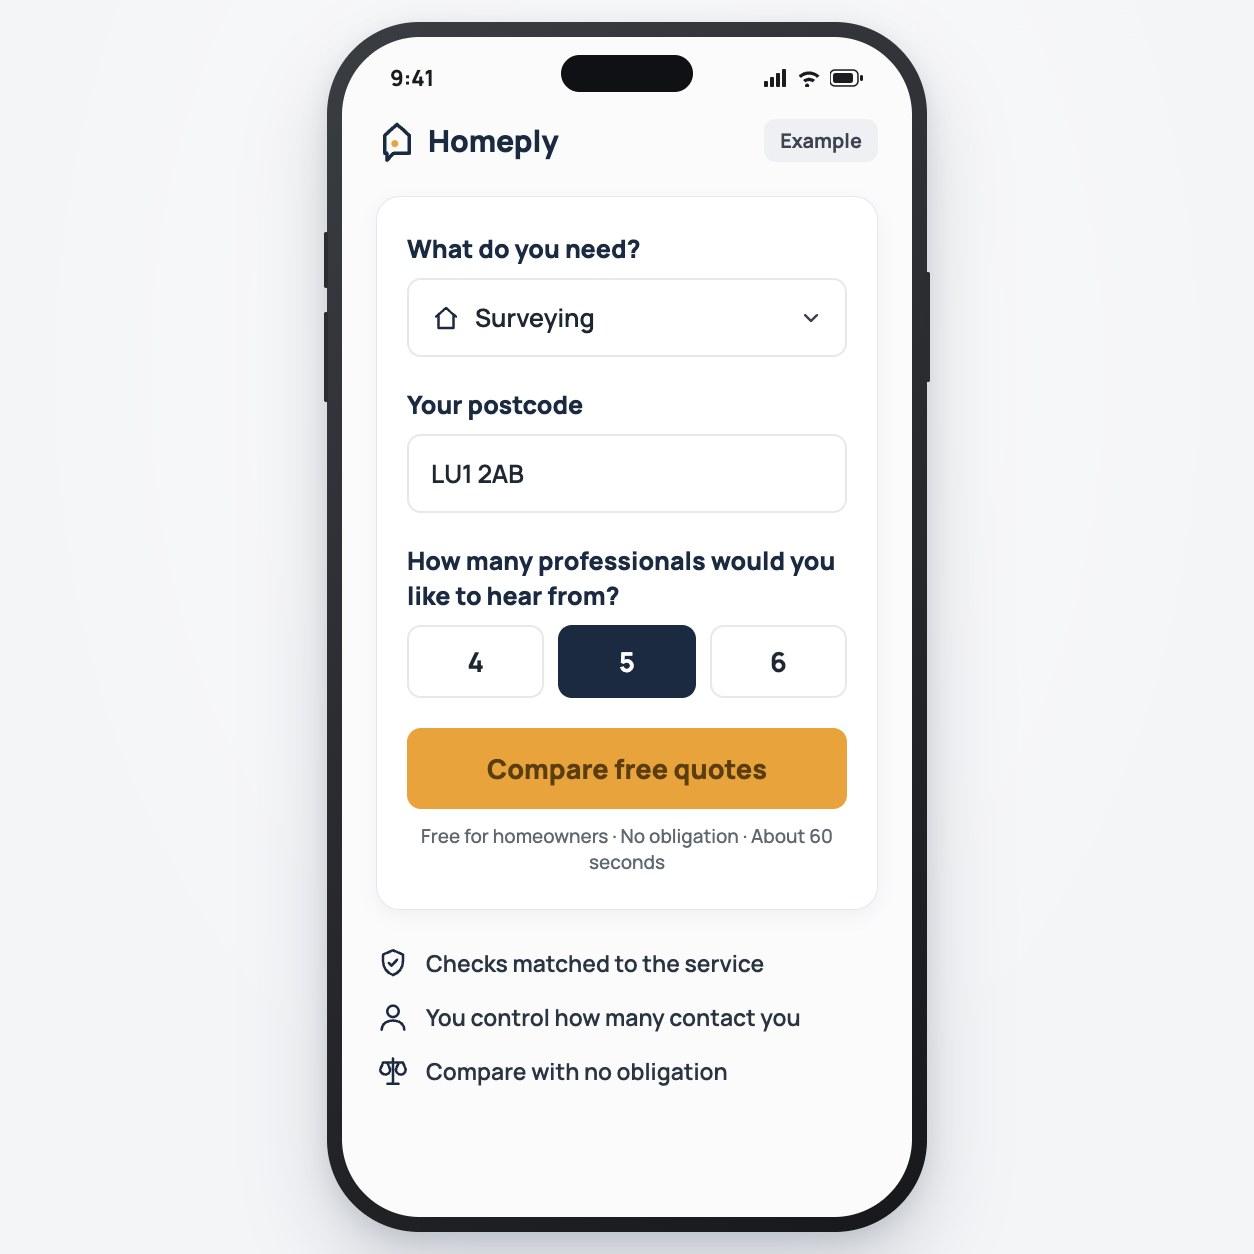
Tell us what you need
Answer a few quick questions about the service, property and postcode. It takes about 60 seconds.
 2
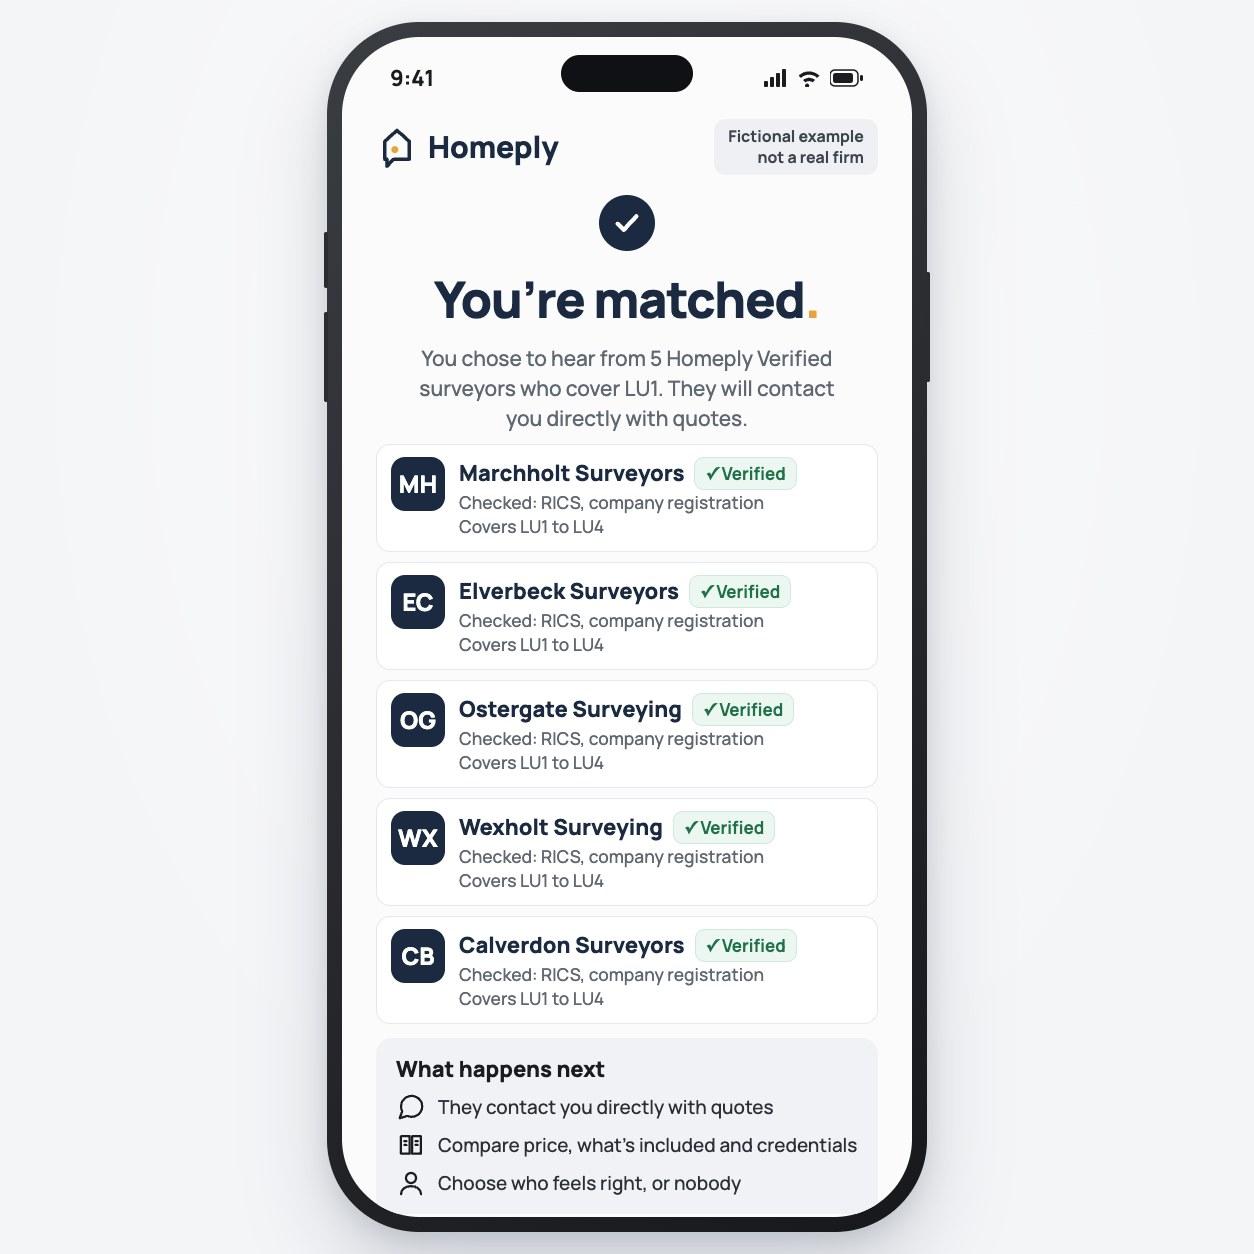
Get matched
We match you with Homeply Verified RICS valuers who cover your area and are taking on work. You choose how many get in touch.
 3
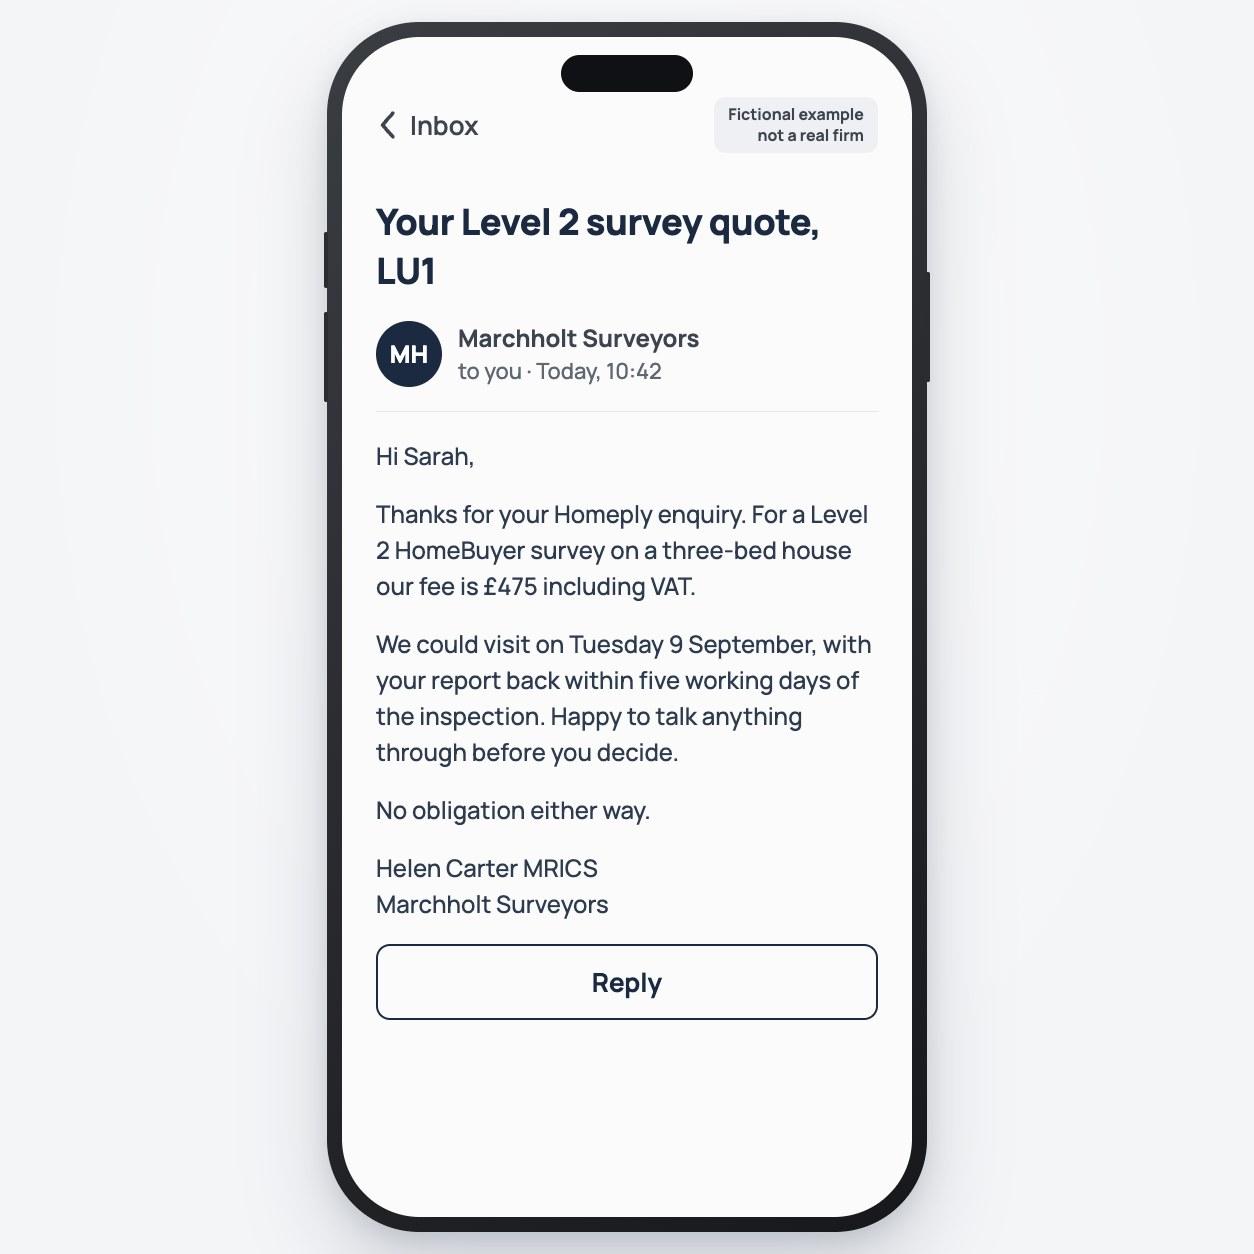
Compare and choose
Your matches contact you directly with quotes. Compare price, what's included and credentials, then choose who feels right.
Your matched valuers get in touch directly with quotes. There's no obligation to instruct any of them.
What Homeply Verified means for Help to Buy valuations
We confirm RICS Registered Valuer status against the RICS register before any enquiry is delivered. Status is re-checked annually, and immediately if a complaint gives us reason to. RICS members carry professional indemnity insurance under RICS rules.
The valuation and the report come from the valuer you instruct, not from Homeply, and your contract is with them. We do the checking; they do the valuing.
See the full standardKnow before you instruct
Plain-English guides and a cost calculator, so you can settle the loan with confidence.
Frequently asked questions
Can I use my mortgage lender's valuation instead?
No. The loan administrator requires an independent RICS Registered Valuer's report commissioned by you, with a physical inspection and comparable sales evidence. Lender valuations, desktop valuations and estate agent appraisals are all rejected.
How long is the valuation valid?
Typically three months from the report date. If your redemption is in progress when it expires, a short extension or desktop update is often possible - ask the valuer about their update fee when you compare quotes.
What does the valuer need from me?
Access for a physical inspection and basic details of the property and any improvements. The report itself goes to the administrator's specification - a valuer who regularly does Help to Buy work will handle the format without prompting.
What if I disagree with the figure?
You can challenge it with evidence - genuinely comparable recent sales the valuer may not have seen - or commission a second valuation. Because the figure directly sets your repayment, it's worth resolving before you submit.
Do home improvements change what I repay?
The valuation reflects the property's current value, and the administrator's rules on improvements are specific - most standard improvements are included in the value. Tell the valuer what you've done and they'll apply the rules correctly.
Ready to settle your Help to Buy loan?
Compare valuation quotesFree for homeowners · No obligation · You choose how many professionals contact you